Your Client Portal
Welcome to your exclusive client portal within The Jasmine Movement. This space has been curated to provide you with comprehensive guidance, transparent expectations, and the resources needed to navigate your credit restoration journey with confidence.
We encourage you to review each category thoroughly rather than skimming, as many common questions and concerns are addressed within these sections. Should you require further clarity after reviewing, you are welcome to schedule a complimentary consultation with our team.
Portal Categories
Select a category below to access specific guidance, policies, and resources
Consultation Desk
Schedule your consultation, understand our availability, and learn the preferred methods of communication.
Rules of Engagement
Service agreements, payment policies, refund terms, and essential client responsibilities.
Growth Obstacles
Common pitfalls that can delay your progress and how to strategically avoid them.
Frequently Asked Questions
Clear answers to the most common questions about timelines, processes, and expectations.
Elite Education
Deepen your understanding of credit scores, reports, and profiles. Knowledge is the foundation of financial mastery.
Action Plan
Step-by-step action items designed to accelerate your credit growth and build a stronger financial foundation.
Digital Library
Essential links, tools, and supplementary resources to support your ongoing financial evolution.
Consultation Desk
Schedule consultations and learn the best ways to reach our team
How To Reach Our Team
- Please do not send unsolicited messages through Facebook Messenger or Instagram. Social media display names often differ from legal names, making it difficult to identify who we are communicating with.
- We do not accept unscheduled phone calls. The most effective way to receive our attention is by booking a consultation through the official link below.
- Due to the volume of clients we serve, responding to hundreds of unscheduled calls and messages daily is not feasible while maintaining the quality of service you deserve.
- A question that appears quick to ask may require a thorough and detailed response.
- For this reason, all questions and concerns must be addressed through a scheduled consultation to ensure every client receives a proper response.
- As an active client, you may schedule consultations at no additional cost.
- Please note that our team may not be available outside of posted business hours, so scheduling ensures your questions are addressed promptly.
- The more structured our communication, the more effective we can be in delivering exceptional results for every client.
Availability: By appointment only — all engagements are scheduled in advance.
Business Hours: Mon – Thu: 12PM – 6PM
This ensures every consultation receives the focused, white-glove attention our active and prospective clients deserve.
Schedule Your Consultation:
Contact Information
Phone: (773) 963-6872
Email: support@thejasminemovement.org
Social Media
Instagram: @thejasminemovement
TikTok: @thejasminemovement
Facebook: The Jasmine Movement
— The Jasmine Movement Team
Rules of Engagement
Essential policies and agreements for all clients
Service Agreement & Payment Structure
Your service agreement with The Jasmine Movement outlines the terms and structure of your credit restoration engagement. It is imperative that you review and understand these terms before or upon enrollment.
Key Terms:
Each dispute round operates on a 45-day cycle (approximately six weeks). Payments are due on or before the start of each cycle to ensure uninterrupted service.
Late or missed payments will result in a pause of services until the account is brought current. We understand life happens — if you anticipate a delay, please communicate with us proactively by scheduling a consultation.
Payment Options: We accept payments through Afterpay, Klarna, Zip, and secure invoicing for your convenience.
Cancellation Rights: In compliance with the Credit Repair Organizations Act (CROA), you have the right to cancel your service agreement within 3 business days of signing without penalty.
Inactivity & Reactivation Policy
Consistent engagement is essential for achieving optimal results.
60-Day Inactivity Rule
If there is no communication, no payment, and no consultation activity for 60 consecutive days, your file will be moved to inactive status.
Reactivation Fee: A $300 reactivation fee is required to resume services after being placed in inactive status. This covers reassessing your file, pulling updated reports, and re-initiating the dispute process.
How to Stay Active: Maintain regular communication, keep your payments current, and ensure your credit monitoring access is up to date. A brief check-in consultation every few weeks is sufficient.
Performance Guarantee & Refund Policy
The Jasmine Movement stands behind our work with a 100% Performance Guarantee.
Our Guarantee: If after 4 complete dispute rounds (approximately 6 months) we achieve zero deletions on your behalf, you are entitled to a full refund of service fees paid.
Conditions for Refund Eligibility:
- Client must have maintained active status throughout the entire engagement
- All required documentation must have been provided in a timely manner
- Client must have responded to all requests for information within specified timeframes
- All payments must be current and up to date
Non-Refundable Items: All DIY digital packages (dispute letter sets, action roadmaps) are non-refundable due to the digital nature of these products.
Proof of Address (POA) Requirements
A current Proof of Address is required before any dispute round can be initiated.
Acceptable POA Documents:
- Utility bill (gas, electric, water)
- Bank statement
- Rental or lease agreement
The document must display your full legal name, show your complete residential address, and be dated within the last 60 days.
Important: An expired or outdated POA will delay your dispute round. If you have recently moved, update your address on your government-issued ID as well.
Growth Obstacles
Common pitfalls that can slow your progress and how to avoid them
Do Not Apply For New Credit During Restoration
DO NOT APPLY FOR ANY NEW CREDIT WHILE UNDER ACTIVE RESTORATION
Every credit application generates a hard inquiry that can lower your score and remain on your report for up to two years.
Why This Matters: While we work to remove negative items, adding new hard inquiries counteracts our progress. Each inquiry signals to lenders that you are actively seeking new debt.
When You CAN Apply: Once your restoration is complete and we have confirmed your reports are clean, we will advise you on the optimal time to apply. Patience during this phase is what separates exceptional results from average outcomes.
Exception: Credit-building accounts in your Action Plan (Kikoff, Self, Chime Credit Builder) are specifically designed to not generate hard inquiries.
The Five-Step Inquiry Filter
Before any application leaves your hands, walk through this five-point checklist. Every inquiry costs you — make each one count.
- 1. Confirm the qualifying score band. Auto financing typically rewards 720+ (680 floor for reasonable terms). For everything else, phone the lender directly and verify. If your profile sits below the threshold, the application is premature.
- 2. Identify the underwriter's true priorities. Mortgage lenders penalize derogatories harshly; landlords often weigh rental history above all else. Ask what factors carry the most weight before submitting anything.
- 3. Assemble verifiable income documentation. Two years of tax returns, recent paystubs, bank statements, W-2s, or 1099s — prepared and organized in advance.
- 4. Know which bureau they pull. If we have cleaned one bureau ahead of the others, route applications toward lenders who pull from the strongest report.
- 5. Inspect the asset before applying. Tour the property or examine the vehicle in person. Any lender who insists on an application prior to a viewing is one to walk away from.
⚠️ While restoration is active, hold every application. A new inquiry undermines the work in progress, and inquiries added during service are not eligible for our dispute process.
🚨 IMPORTANT: When Can I Start Applying For Things?
If derogatory items remain on your report, the answer is straightforward: applications wait. We approach the market only after the file is clean and inquiries sit at two or fewer per bureau.
An honest assessment:
- The score reflects years of accumulated damage
- Multiple derogatories continue to weigh on the file
- Positive payment history has not yet been established
- Restoration is a process — not a thirty-day transaction
Pursuing approvals before the foundation is set produces denials, frustration, and additional inquiries. The disciplined path delivers the result. Meaningful progress — even partial progress — compounds; we will reach the destination in the proper sequence.
The full criteria before any application:
- ✅ Credit Score minimum 680, preferably 720+
- ✅ Credit Card Utilization under 10%
- ✅ 0 Negative Derogatory Accounts
- ✅ 0 Delinquent Accounts (Late Payments)
- ✅ 2 or fewer Inquiries per bureau
Protecting Your Profile When a Payment Is at Risk
Reach out to the creditor before a payment is missed — never after.
A useful framing for the call: "My finances are experiencing a short-term strain. I want to remain current on this account. What relief options does your hardship department offer?"
Lender hardship programs typically include:
- A reduced monthly payment
- A temporary interest-rate concession
- A short pause in payments
- A repositioned due date
👉 This single conversation is the most effective protection your credit has.
- Request a Payment Deferral or Skip-A-Payment. Auto lenders in particular will often defer one to three installments to the end of the loan while reporting your account as current.
- Anchor a minimum-payment safety net. Configure autopay for the minimum on every revolving account. Even a small posted payment prevents the thirty-day late from ever reporting.
- Realign the due date with your pay cycle. Most lenders permit this with a single phone call.
The action sequence:
- Place the call today — not tomorrow
- Request hardship status or a deferral in writing
- Post at least the minimum payment where possible
- Track every due date manually until the matter is resolved
👉 It is the conversation — not the silence — that preserves your credit.
⚠️ Without intervention: auto loans move toward repossession; revolving and installment accounts charge off between 120 and 180 days; balances are sold to collections.
Do Not Pay Off Collections Without Consulting Us First
Do Not Pay Collections Without Our Guidance
Paying off a collection does not remove it from your report. In many cases, it can restart the reporting clock and lower your score further.
The Right Approach: We employ strategic dispute methods to remove collections entirely. If payment is necessary, we will guide you through negotiating a "pay for delete" agreement.
Common Mistake: Paying off collections and finding it now shows as "Paid Collection" — which still negatively impacts your profile. Always consult us before making payments toward items we are actively disputing.
Maintaining Low Credit Utilization
Revolving utilization is responsible for roughly thirty percent of the FICO calculation. Of every variable inside the model, this is the one you control most directly — and the one that responds the fastest.
The Movement standard: hold reported balances at or below 10% of each card's limit. Anything beyond 30% begins to compress the score noticeably.
Reporting timing: the balance the bureaus see is the balance posted on the statement closing date — not the due date. Paying down approximately 72 hours before the statement closes is what reports a low utilization figure.
The trap to avoid: a card carried near its limit through the statement close — even if zeroed out a week later — still posts to your report as a high utilization snapshot. Pay timing matters as much as pay amount.
The Devastating Impact of Late Payments
Payment history is 35% of your credit score. A single late payment can drop your score by 60-100 points and remain on your report for up to 7 years.
Every Payment Must Be On Time
If we are working to clean your report and you simultaneously add new late payments, it undermines the entire process.
Best Practice: Set up autopay for at least the minimum payment on every account. You can always pay more than the minimum manually.
Grace Period: A payment is not reported as late until 30 days past due. However, you may still incur late fees before that mark. Always pay on or before the due date.
Frequently Asked Questions
Clear answers to the questions we hear most often
How Long Does The Restoration Process Take?
Every credit profile is unique. Most clients experience their complete financial transformation within 6 to 9 months.
Dispute Cycle: Each round operates on a 45-day cycle. Updates are provided according to this timeline and depend on all required documentation and monitoring access being current.
Factors That Influence Timeline:
- Number of negative items on your report
- Types of derogatory marks
- How quickly you provide required documentation
- Whether your credit monitoring stays active and updated
- Your adherence to the guidelines in this portal
The fastest results come from following every guideline, providing documents promptly, maintaining monitoring, and avoiding actions that create new negative marks.
How Do Updates Work & When Will I Hear From You?
Update Timeline: Each dispute round operates on a 45-day cycle. Updates are scheduled accordingly and depend on all documentation and access being current.
Phase One: Proof of Address
We confirm a current POA is on file — dated within the last 60 days.
Phase Two: Credit Monitoring Access
We verify your monitoring is active (paid) and updated (refreshed).
Phase Three: Dispute Submission & Results
Disputes are submitted and bureau response times are typically 30-45 days. We will contact you with a detailed update once results are in.
Please be patient. Reaching out repeatedly before the 45-day cycle completes does not accelerate the process. We will contact you as soon as results are available.
Can I Check My Own Credit During The Process?
Yes. Checking your own credit is a soft inquiry and does not affect your score.
Safe to check: Your monitoring service, Credit Karma, pre-qualified offers, employer background checks.
Avoid: Applying for new credit (loans, credit cards, financing) — these generate hard inquiries that impact your score.
What Is Credit Monitoring & Why Is It Required?
Credit monitoring gives both you and our team real-time access to your credit reports from all three bureaus.
Why We Need It:
- See exactly what is on your report across all three bureaus
- Track which items have been removed after each dispute round
- Access detailed account information needed for effective dispute letters
Your Responsibility: Keep your account active (paid) and updated (refreshed). These are two different actions.
Setup Links: Available in the Digital Library section of this portal.
Elite Education
Master the fundamentals of credit to accelerate your financial evolution
Understanding Your Credit Score
Your credit score is a three-digit number representing your creditworthiness. It determines approval, interest rates, and credit access.
The Five Factors:
1. Payment History (35%) — Are you paying on time?
2. Credit Utilization (30%) — How much credit are you using?
3. Credit History/Age (15%) — How long have you had credit?
4. Credit Mix (10%) — What types of credit do you have?
5. Hard Inquiries (10%) — How often are you applying?
Ideal Benchmarks:
Payment History: 100%
Credit Card Utilization: 10% or below
Derogatory Marks: 0
Credit Age: 5 years or more
Total Accounts: 10 or more
Hard Inquiries: 2 or fewer
Credit Age Calculator
Determine the average age of your credit accounts
Your Average Credit Age
Credit Utilization Mastery
Utilization is your balance-to-limit ratio — 30% of your score.
Formula:
Utilization = (Total Balances ÷ Total Credit Limits) × 100
Tiers:
0-10%: Excellent | 11-30%: Good | 31-50%: Fair | 51-100%: Poor
Utilization Calculator
See where your credit utilization stands
Your Utilization Rate
Debt-to-Income Ratio Explained
DTI is the percentage of gross monthly income going toward debt payments. Critical for loan approvals.
DTI = (Total Monthly Debt ÷ Gross Monthly Income) × 100
Counts as Debt: Credit card minimums, auto loans, student loans, personal loans, mortgage/rent, child support
Does NOT Count: Utilities, cell phone, insurance, groceries, subscriptions
DTI Guidelines
0-35%: Excellent | 36-43%: Acceptable | 44-50%: Risky | 50%+: High risk
Why DTI Matters
You can have a 750+ score and still be denied because of high DTI.
DTI Calculator
Find your Debt-to-Income ratio
Your DTI Ratio
The Credit Application Process
The Application Is Your Interview
Even with a strong score, inconsistent personal information across reports can trigger denials.
You want: ONE name, ONE date of birth, ONE employer — matching exactly across all three bureaus.
Prevention: Ensure your ID address matches your current residence. Use the same personal information consistently on every application.
Understanding Your Credit Report
Your Credit Report Is Your Financial Background Check
This is what ultimately determines approval or denial.
Never underestimate the impact of even a single collection. One collection can result in denial regardless of amount owed. Smaller collections can appear worse — they signal irresponsibility with basic obligations.
What A Clean Report Looks Like
Payment History: 100% | Utilization: 10% or below | Derogatory Marks: 0
Credit Age: 5+ years | Total Accounts: 10+ | Hard Inquiries: 2 or fewer
If your report does not reflect these benchmarks — that is exactly why you are here.
Note: One collection reporting on all three bureaus appears as three negative marks on paper. Your report often looks worse than reality.
Building A Premier Credit Profile
Your Profile Is What Sets You Apart
Two applicants with the same score, same number of accounts, and same payment history are NOT equal. The profile reveals deeper details.
Key Differentiators:
Credit History (15%) — the longer, the more trustworthy
Credit Mix (10%) — diversity signals financial sophistication
The longer the history and the more diverse the mix, the stronger the profile
This is why the Action Plan matters. Building credit accounts now establishes the foundation for a premier profile. Every month of on-time payments and low utilization strengthens your position.
Your To Do List
Action items to help boost your credit score and build strong credit. These are the things you should be doing on your end.
TO DO LIST Template
One of the most common questions clients ask me “IS THERE ANYTHING I SHOULD BE DOING ON MY END?”
May I remind that there’s a BIG DIFFERENCE Between your Credit SCORE, Credit REPORT, and your Credit PROFILE. These are 3 COMPLETELY DIFFERENT THINGS & are not to be mixed up. Which means it is important to understand that Credit REPAIR focuses on your Credit REPORT. NOT THE SCORES & PROFILE.
Credit REPAIR DOES NOT build your Credit PROFILE, & it also DOES NOT BOOST YOUR SCORES! This means I CAN NEVER be the reason your credit scores haven’t gone up or the reason they may have dropped. Although I can’t physically make your scores go up ⬆️ I can give you a Step By Step Action Plan to increase your scores and build a strong profile. This is how we raise our scores from the 300s to the 700s plus.
The TO-DO-LIST was designed to help build payment history, strengthen your credit profile, build better relationships with banks, to help you qualify for things such as Credit Cards, Auto & Mortgage Loans, and even Personal & Business loans in the future. If your scores are truly important to you. We recommend that you complete as many steps on this To-Do-List as you can. If you are confused about a certain step, you can always book a CONSULTATION.
🚨 Important Notice
- ✅ You DO NOT HAVE TO WAIT FOR EVERYTHING TO BE DELETED to start on your to do list. YOU CAN START ON THIS NOW.
- ✅ If a step has already been completed and is already active on your credit report, you can Skip To The Next Step.
- ⚠️ STEPS 4 & 5 ARE ESPECIALLY IMPORTANT FOR THOSE WHO ARE LOOKING TO REFINANCE OR FINANCE A CAR. OR APPLY FOR ANY LOANS MORTGAGE, PERSONAL, or BUSINESS
- ✅ Even if you can’t do Steps 3-7… YOU CAN DO STEPS 1-2 & 8. And You Can Start RIGHT NOW.
- ⚠️ If you are in ChexSystems or Early Warnings you may not be able to do steps 4 & 5. If this is the case, go to my FAQ Tab to see how to get removed.
What Happens If I Don’t Complete My To Do List?
Although it is in every client’s best interest to complete this phase of the program please understand that This to-do-list is NOT MANDATORY. I cannot force anyone into completing this phase nor will I continuously follow up or pressure clients to do so.
To Do List Step 1
Remove All Fraud Alerts 🚨
⚠️ If you have no fraud alerts on your report you can skip this step and move on to Step 2.
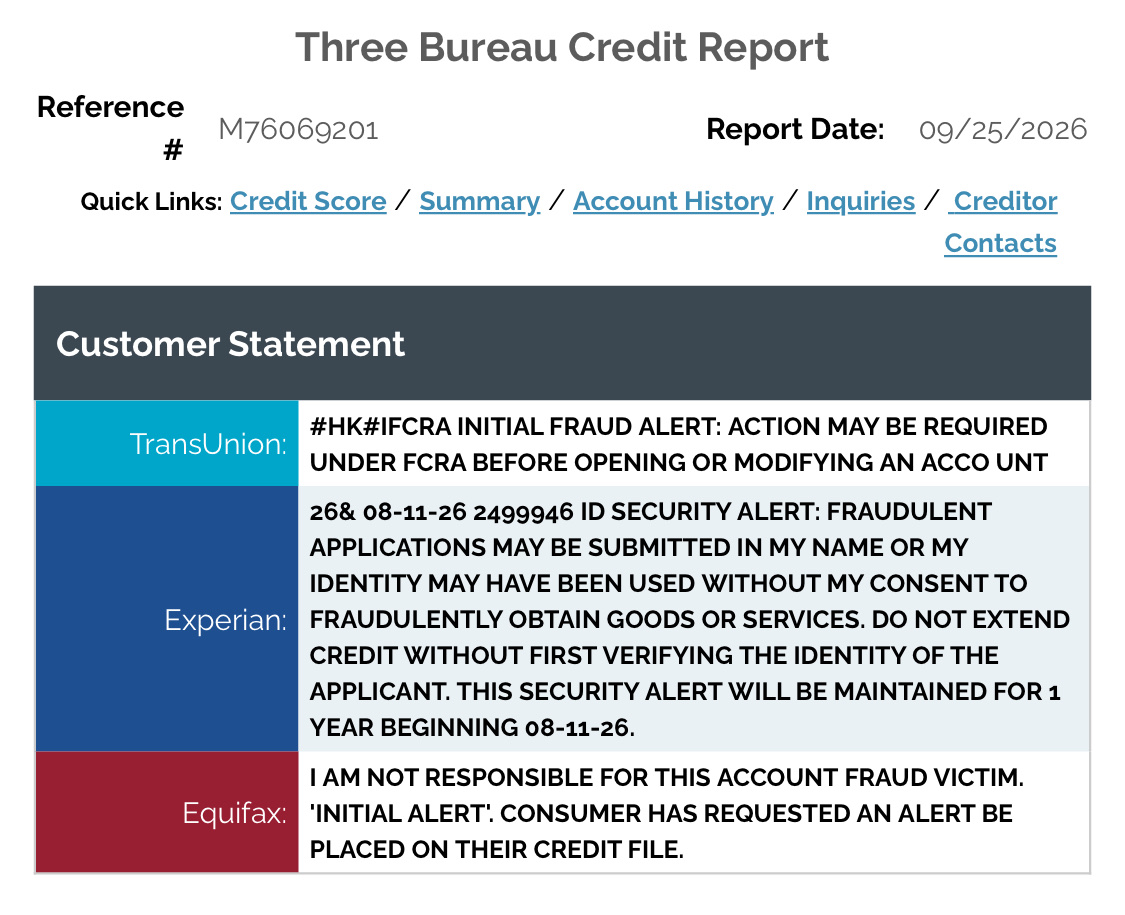
No worries a fraud alert is NOT A BAD THING. It is a free safety tool that helps protect you from identity theft.
A fraud alert is a notice placed on your credit reports that tells lenders and creditors to take extra steps to verify your identity before approving new credit in your name. That extra step is usually to text or call you for confirmation before actually running your credit.
Although this is a safe way to protect yourself from identity theft—having an active fraud alert can delay the process because a fraud alert is a strict security feature. The credit bureaus will not process any changes, updates, or actions on your credit report while it remains active and we do not want that.
To resolve this, our team has already sent a request letter to the bureaus on your behalf to remove the fraud alert. However, waiting for the bureaus to process mailed requests can take some time and we do not want to depend on them removing the alerts. To expedite the process, we highly recommend that you call the three credit bureaus directly to request the removal or deactivation of the alert.
Please note that you can do this online. Calling them is completely optional, but doing it over the phone bypasses mail processing times so we can resume work on your credit report much faster.
If you choose to call them, you can reach the fraud divisions at the following numbers:
📞 Equifax: 1-800-525-6285
📞 Experian: 1-888-397-3742
📞 TransUnion: 1-800-680-7289
If you choose to do it online here are the exact links:
Once you have the alerts deactivated, please let us know as soon as it is completed so we can immediately continue working on your file. Once we’re done working on your profile, feel free to add them back if you like.
The Representative will most likely ask you if there’s anything else they can help you with? Say One More Thing, and SEE STEP 2 FOR DETAILS.
Thank you for your cooperation!
To Do List Step 2
Call To Clean Up Your Personal Information 📞
THIS IS NOT MANDATORY. However, THIS STEP IS TO HELP US EXPEDITE THE PROCESS.
Please understand WE ARE DOING ALL OF THE HARD WORK FOR YOU. However, the most we can do is send out dispute letters. We only ask for your assistance if it helps speed up the process and if it involves you actually calling The 3 Major Credit Bureaus.
If we were to call on your behalf, we most likely would fail the verification stage due to lack of knowledge about you & your family’s history. We do not have a list of what questions they will ask. These are not all, but some common questions are..
- What is your mother’s maiden name?
- What hospital were you born?
- Which of these were your previous phone number?
- What was your first car.
- Which one of your family members lives in ____?
The list goes on and won’t be able to answer all security questions correctly. Which is why we are asking for your help. Help us help you!
Credit bureaus often tie negative accounts (like collections, charge-offs, & late payments) to old addresses, previous phone numbers, and misspellings of your name. By calling them to delete this outdated information as we dispute the negative items, we can break the link between you and those bad accounts.
While we can still proceed without you doing this, you taking 15-20 minutes to make these calls can drastically shorten your time in our program and increase our success rate.
Equifax
Phone: 1-866-349-5191 (or 1-800-685-1111)
Hours: Monday – Friday, 9AM to 9PM
Prompt Navigation: Press 1 for English, then say “Agent” or press 0 to speak to a representative.
Experian
Phone: 1-888-397-3742
Hours: Monday – Friday, 8AM to 6PM
Prompt Navigation: Press 2, then press 1, then press 3 to route to a live agent.
TransUnion
Phone: 1-800-916-8800
Hours: Monday – Friday, 8AM to 11PM
Prompt Navigation: Press 1 for English, then press 4, then press 1 to speak to an agent.
Before you call, make sure you have:
- Your Social Security Number
- Your current address and previous address
- Your driver’s license or state ID
The Phone Script (Read this to the representative)
Please call Equifax, Experian, and TransUnion using the numbers above. To make this as easy as possible, we have provided a script for you to read to the representatives. See Dropdown #4 – The Script.
“Hello, my name is [Your Full Name]. I am reviewing my credit file and noticed several inaccurate and incomplete personal identifying information being listed under my personal information.
I want to correct all inaccurate information.
MY ONLY NAME IS: [Correct Name]
MY ONLY DOB IS: [Correct DOB]
MY ONLY ADDRESS IS: [Correct Address]
MY ONLY Employer IS: [Correct Employer]
Under the FCRA (Fair Credit Reporting Act) I am requesting that my credit file reflect accurate identifying information consistent with the FCRA’s accuracy requirements under 15 U.S.C. § 1681e(b). Can you please delete all other addresses, employers, and incorrect name variations from my profile for me, because it’s holding me back from getting approved from housing which is a violation of my consumer right. As they are invalid.” Can please process this for me right now and provide confirmation of the results?
Ask how long it will take before your credit report will show up.
If the representative tells you that an old address cannot be deleted because it is tied to an active trade line, politely reply:
“That address is not valid or safe for my profile. I need it removed from my personal information section immediately to prevent any potential fraud or confusion.”
If they still refuse to remove the information simply say….
“If you are declining to correct or delete the disputed information, please complete the dispute investigation and provide me with the results in writing, including your determination regarding the information I disputed.”
They may ask you to send them a “cover letter”. Please make sure your State ID or Driver’s License is updated with your current address BEFORE sending out this cover letter.
Addresses:
- Equifax: P.O. Box 740256, Atlanta, GA 30374
- Experian: P.O. Box 4500, Allen, TX 75013
- TransUnion: P.O. Box 2000, Chester, PA 19016
Date: __________
To Whom It May Concern,
I am writing to verify my identity so that my [Bureau Name] credit report and score can be released and made available.
My information is as follows:
Full Name: __________________________
Date of Birth: ______________________
Last 4 of SSN: ______________________
Current Address: ___________________
City, State, Zip: ___________________
Phone Number: _____________________
I have enclosed copies of my government-issued photo ID and proof of address for verification. Please process my identity verification as soon as possible so my credit file can be properly displayed.
Sincerely,
________________________ (Signature)
________________________ (Printed Name)
Documents to Include (VERY IMPORTANT):
✅ Copy of Driver’s license or state ID (cannot be expired)
✅ Proof of address (utility bill, bank statement, or lease — dated within 60 days)
To Do List Step 3
Become An Authorized User
If you have a family member or a close friend who has good credit, ask them to add you on their credit cards as an Authorized User. This can help improve your scores WITHOUT AFFECTING THEM AT ALL.
When you are added to a credit card it's going to show up on your credit report as an authorized user (this lets the banks know that you have ACCESS to that card).
Example: If someone has a $10,000 Chase credit card and they had it for 10 years, the utilization is reporting below 10%, and they are always on top of their bill - this does multiple things for you:
- 1) Payment History (35% of your credit score) - It gives you 10 years worth of PAYMENT HISTORY
- 2) Utilization (30% of your credit score) - That $10,000 limit gets added to your Debt To Income Ratio
- 3) Credit Mix (10% of your credit score) - That credit card would be considered a revolving account
- 4) Credit Age (15% of your credit score) - It also would be 10 years worth of Credit Age History
So this is why people's scores go up whenever they purchase tradelines.
If someone is skeptical about adding you as an authorized user, please explain this to them:
YOU DO NOT NEED THE CARD! They can have it sent to them and they can then cut it up. You just need it to piggy back off the history.
Whenever someone adds you as an authorized user it could affect you, but NEVER THEM. Reason being is because when they add you on that account, usually it means that you have access to THAT ACCOUNT. Which means whatever happens with that account YOU'RE JUST AS RESPONSIBLE. Now of course that won't be the case if they sent the card to them and cut it up, but that's still how banks & lenders will look at it.
On the flip side you can be late on every credit card you have and it would not affect them at all. They can be late for every other credit card they have as well without affecting you negatively. The only thing that matters are the specific accounts that you are listed as a AUTHORIZED USER.
Good Authorized User Vs Bad: Things To Look For
GOOD AU - Things To Look For:
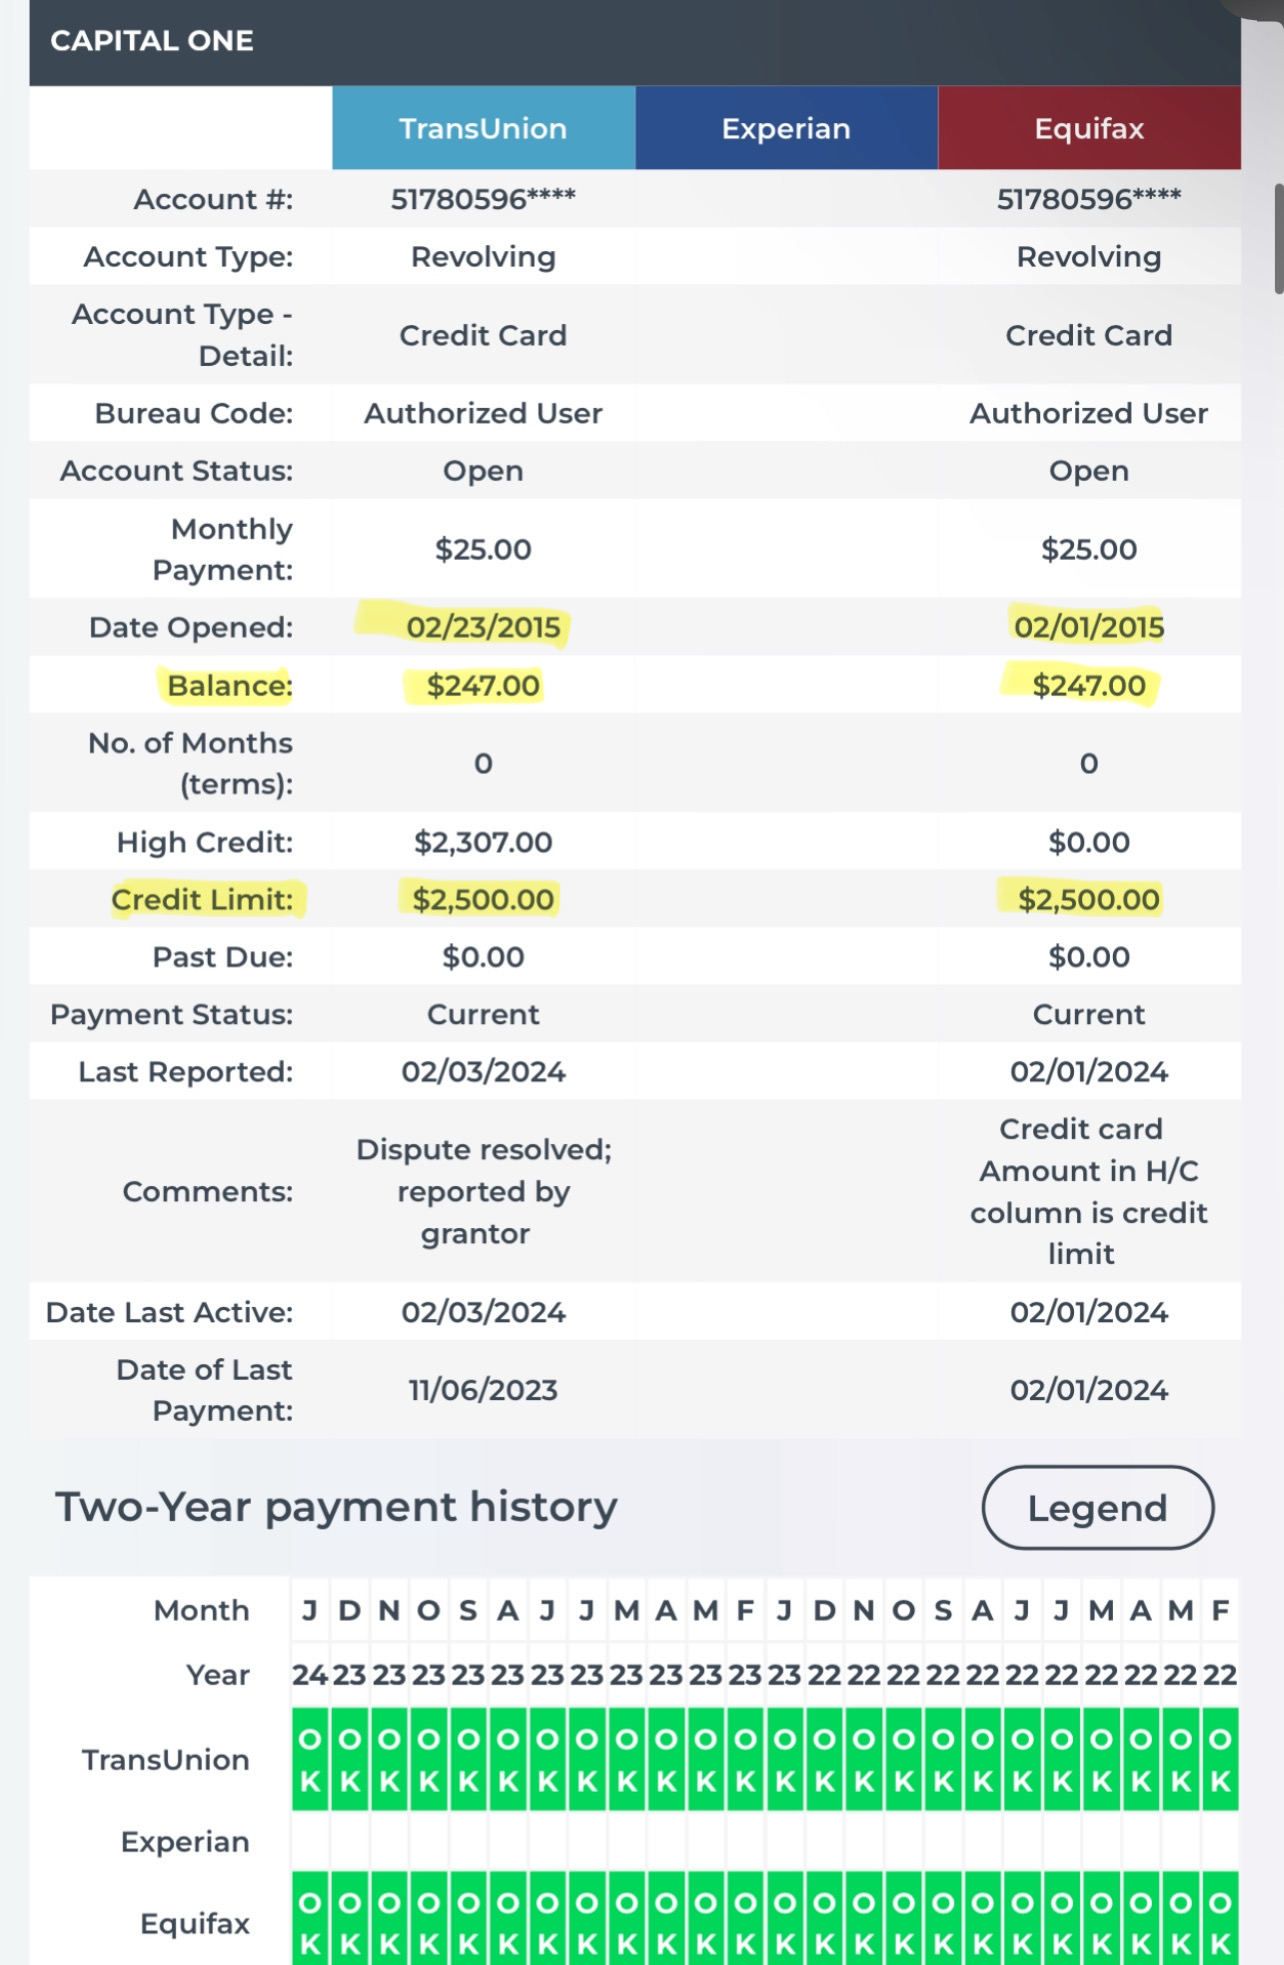
- Payment History - 35% Of Your Credit Score. This Account Has No Late Payments
- Credit History - 15% Of Your Credit Score. This Account Was Opened In 2015 So That's 11 Years Worth Of Credit History (Bank's Like To See 5+ Years)
- Credit Limit - Although We Would Prefer Something Over A 5K Limit, $2,500 Is Not Bad Especially If You Don't Already Have Your Own Account With That Limit. Keep In Mind It Has The History To Back It.
- Credit Card Utilization - 10% Of Your Credit Score. This Credit Limit Is $2,500 Which Means 10% Is $250. And 30% = $750. The Balance Is Only $247 Which Means It's Under 10%. THAT'S WONDERFUL.
This AU IS GOOD TO GO
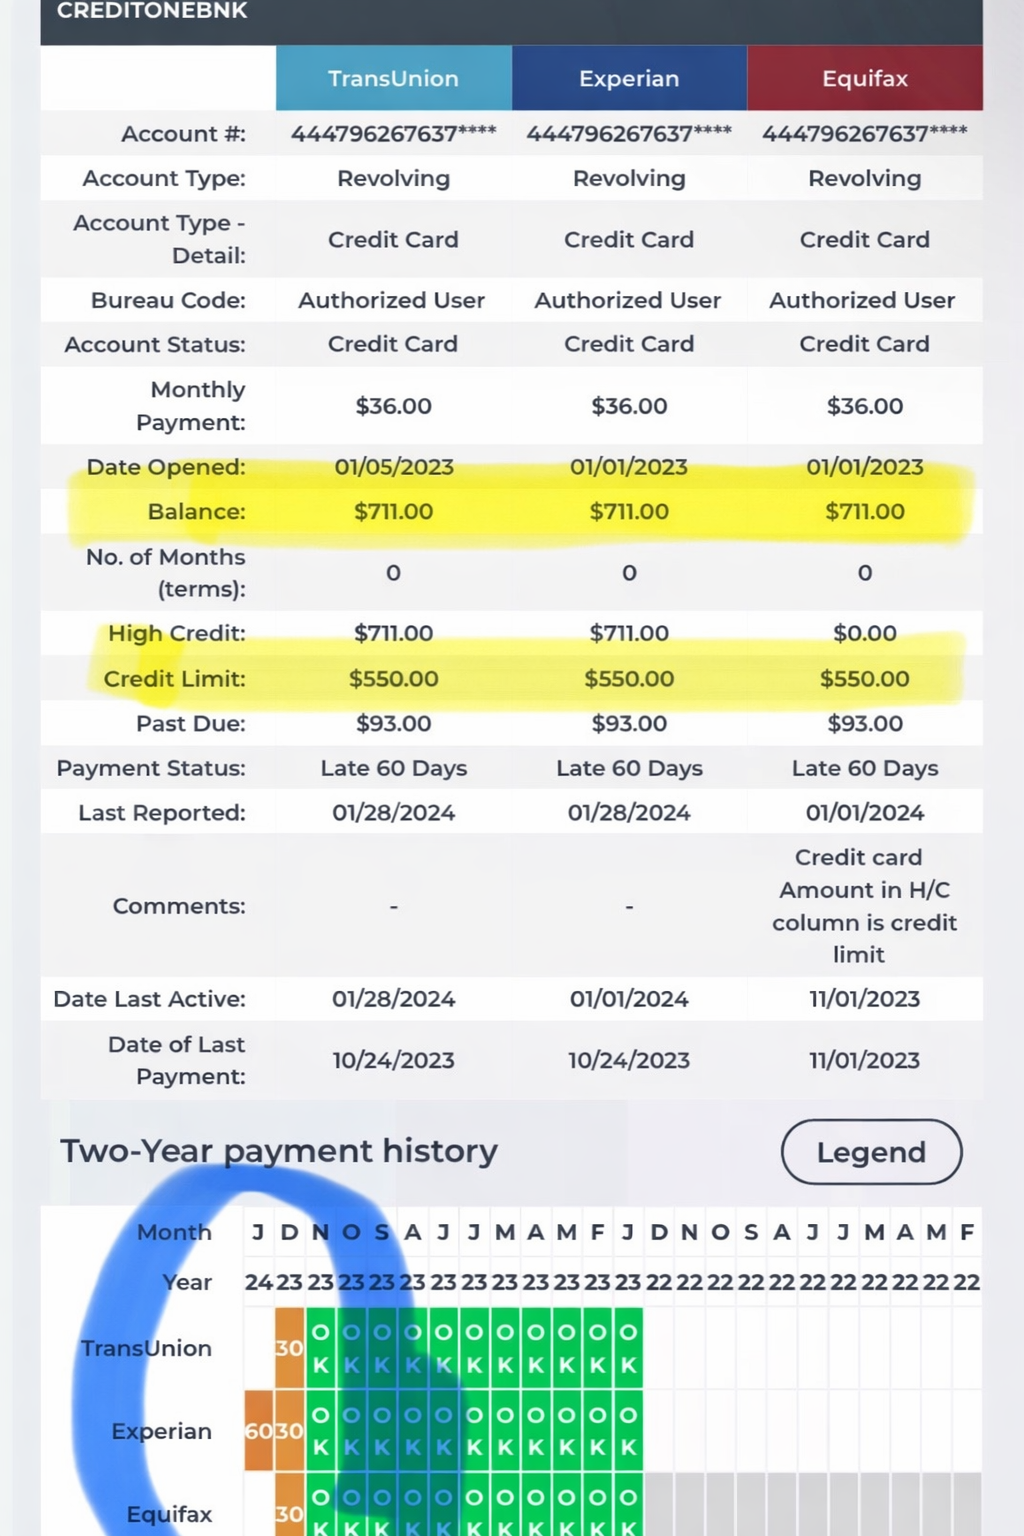
BAD AU - Red Flags:
- Payment History - This Account Has Multiple Late Payments (RED FLAG)
- Credit History - Only 3 Years Old. The Banks Like To See 5+ Years. 3 Is Only Acceptable If Everything Else Checks Off or if it is better than your actual credit age itself.
- Credit Limit - $550. The Banks Like To See A Minimum 5K Limit
- Credit Card Utilization - This Credit Limit Is $550 Which Means 10% Is $55. And 30% = $165. With a balance of $711 which is higher than the actual credit limit. This Card Is Clearly Maxed Out
This AU Is A NO GO. If you're listed on a card like this you need to ask the primary owner to remove you immediately or call the creditor for help.
To Do List Step 4
Part 1. Open Up A PERSONAL Checking & Savings Account With A CREDIT UNION
ALWAYS START WITH THE SAVINGS ACCOUNT FIRST FOR ANY BANK… Then The Checkings.
SIDE NOTE: If you are currently listed in ChexSystems or Early Warnings then you will most likely be denied for this step. You can visit TheJasmineMovement.org/faq and look for ChexSystems / Early Warnings to request your consumer report. If you need assistance getting out I can definitely help. However that is a separate charge, as checking is separate from credit.
If you ARE NOT listed in ChexSystems / Early Warnings then you can start this step RIGHT AWAY. If you are already a part of a credit union you can use them, or you can literally google “credit union near me”, open an account and do a secured loan. If you can’t find a credit union you can also do this with whoever you currently bank with, but a credit union would be the better option.
I will list my top 4 recommendations below. Navy Federal is the top choice only because it works best with STEP 5. But realistically, IT DOES NOT MATTER WHICH ONE YOU CHOOSE.
⭐ Navy Federal (Top Choice — works best with Step 5)
- Low interest rates
- Outstanding credit card approvals
- ATM fee reimbursement
- Great with auto loans & refinancing
Membership is open to service members, veterans, Department of Defense employees, and their families. Check whether you qualify on their membership page before applying. If you are not eligible, any of the other credit unions below work just as well.
If they ask why you want an account with them, tell them you want to build a LONG TERM RELATIONSHIP WITH THEM.
They’re going to ask what type of account you want to open. Say regular personal checking and savings. You will need to deposit a minimum of $10–$20 to open the account. If you can, I recommend putting $100 in both (see Part 2 for more instructions).
They will ask if they can assist you with anything else — you can say no for now.
Open An Account →🏦 Consumers Credit Union (CCU)
- Good for auto loans
- Anyone can join
- Interest rates as low as 5%
- Will fund you up to 100% of the car’s book value
- Loan terms up to 84 months
💻 Digital Credit Union (DCU)
- Good for auto loans
- Anyone can join
- Interest rates as low as 5.74%
- Will fund you up to 130% of the car’s book value
- 84 month terms, & a delayed payment for 60 days
🏛️ PenFed Credit Union
- Good for auto loans
- Rates as low as 4.49%
- Can finance up to 125% of the car’s book value
- Can get a pre-qualification before the approval, meaning you don’t have to take a hard inquiry
Part 2. Deposit Money In Both Checkings & Savings
Once you have chosen your desired credit union or bank, deposit money in both the checking & savings. The more the better, but do whatever is comfortable within your budget. We call this the 50/50 plan.
Examples:
• $100 in Checkings & $100 in Savings
• $500 in Checkings & $500 in Savings
• $1,000 in Checkings & $1,000 in Savings
• $5,000 in Checkings & $5,000 in Savings
Part 3. Set Up Direct Deposit
If you get direct deposit, I prefer you to have it transferred to the credit union or bank you signed up for. If not your entire check, at least half. I understand some of you may love Chime, Cash App, PayPal etc. so that you can get paid early or whatever the case is. But understand Chime will not give you a $30,000+ auto loan or a $100,000+ business or mortgage loan.
So realistically speaking, the bank who will be splurging on you in the near future is the bank who deserves your money. Trust me, this will benefit you a whole lot later down the line when you start applying for things.
If you work for yourself and don’t have an actual 9-5 where you receive check stubs, it would be smart to just make sure you’re CONSISTENTLY making weekly, biweekly, or monthly deposits.
To Do List Step 5
Open Up A Secured Loan For $2,500 💵
( Don’t worry — you will get your money back. )
Don’t stress if you don’t have $2,500. The minimum requirement for a secured loan is $250. I recommend $2,500 because realistically speaking — what looks better? That you paid off a $250 loan, or a loan for the amount of $2,500+?
You can go higher. OBVIOUSLY THE MORE THE BETTER.
- If you don’t have $2,500 try $1,500
- If you don’t have $1,500 try $1,000
- If you don’t have $1,000 try $500
- If you don’t have $500 try $250
You can do this with literally ANY BANK OR CREDIT UNION. Your collateral is still your money. However, depending on the financial institution, some or all of it may remain unavailable to you until you repay the corresponding portion of the loan.
This is why I recommend to specifically do this with Navy Federal — because unlike many traditional credit unions and banks, they don’t require you to wait until the end to receive your money back. You can have your money back within 10 business days.
Short Answer: A secured loan is basically borrowing against money you already have.
Why do people do this? The goal isn’t to borrow money because you need the money. The goal is to establish positive LOAN payment history, and to strengthen the credit profile. It’s a lot easier to get approved for loans if you have already proven you can pay some.
Taking out a secured loan is equivalent to you going to a bank or credit union and saying:
“Hey look, I understand that based on some mistakes I have made in the past, you may not be comfortable giving me a traditional loan right now. But I want to prove to you that I’m now responsible. So instead, I am asking to borrow some money, but I am also willing to put up my own money as collateral to prove that I can responsibly make payments on a loan. If I don’t pay it back you keep my money and you take no risk. But if I do pay it back on time, now you give me back my money and do business with me.”
Remember… “YOUR CREDIT” is your credibility. And unless you have already paid off a house, a car, or plenty of other loans in the past, right now with these negative accounts on your report you have no credibility. So when you do a secured loan it’s kind of as if you paid someone to report on your credit report that you have successfully paid off a loan.
Secured loans were designed to give you a 2nd chance and make you look good on paper. THAT’S IT, THAT’S ALL. Please do not over think it.
Call or go into Navy Federal and open up a SECURED PLEDGE LOAN for $2,500. (If you do this with another bank it’s just called a secured loan.)
When you request to put down $2,500 for the secured loan, the bank will take that $2,500 out of your savings account and deposit it into a SEPARATE SAVINGS ACCOUNT.
Important
Then wait one week and call back and say you want to pay it off 90% and leave the rest on autopay for the next 12 months. DO NOT pay off the full balance and DO NOT forget to mention AUTOPAY. The goal is to get majority of the loan out the way, but also to leave a history of on-time monthly payments. (35% of your credit score)
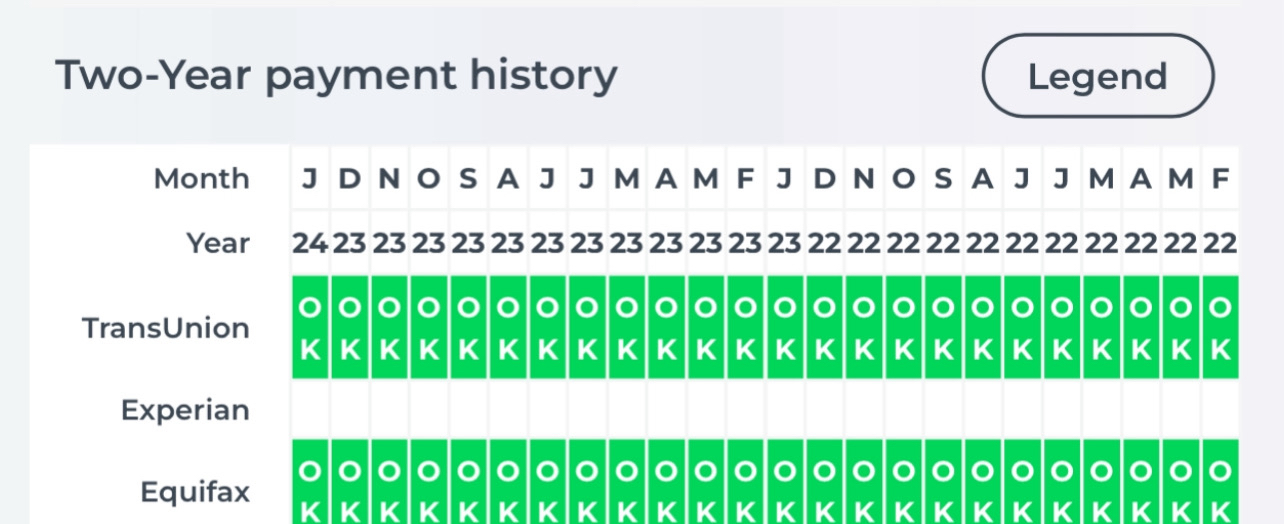
You are not coming out of pocket again. You are paying them back with the same exact money you gave them.
So when you say you want to “pay back 90%”, they will take $2,250 out of the $2,500 that you gave them, and deposit it back into your checking or savings account. (Whichever you decide — it doesn’t matter.)
Now, instead of $2,500, the new balance you owe for the secured loan will be $250. For the next 12 months that $250 will be on Autopay. So every month they will take about $21.25 out of that separate savings account and deposit it back into your checking or savings account until that number hits $0.
The next time your credit report updates, it will show that you paid off a $2,500 loan by 90% — even though you never actually took out an actual loan. You can take that same money and do it again.
It’s not mandatory, but it’s always best to do this at least twice. Every time you do this, try to double or triple the previous amount you did it for.
If you have Navy Federal, this step is NOT for you — unless you want to do it again with another bank or credit union, which is completely fine.
Call or go into the credit union or bank you decided to join or already have. Tell them you want to open up a SECURED LOAN for $2,500.
When you request to put down $2,500, the institution places that $2,500 into a SEPARATE SAVINGS ACCOUNT and puts a hold on it. It’s still your money, but you generally can’t withdraw it while it’s securing the loan.
The institution then lends you $2,500. Once approved, they give you the loan. So you put up $2,500 as collateral and received approximately $2,500 back as “borrowed money.”
You now owe the $2,500 loan plus interest. For example, on a 12-month term, your payment might be roughly $215–$225 per month, depending on the interest rate and fees.
$225 × 12 = $2,700
$2,700 − $2,500 = $200
These numbers aren’t final — this is just an example. So you’re only coming out of pocket an extra $200. Look at it as if you’re BUYING CREDIT.
Important
Then wait one week and call back and say you want to pay it off 90% and leave the rest on autopay for the next 12 months. DO NOT pay off the full balance and DO NOT forget to mention AUTOPAY.
So the $2,500 that they let you borrow — use that same money for the monthly payments to pay down 90% of the loan. The lender typically reports the loan and payment history to the credit bureaus.
Now your new balance for the secured loan will be $250 instead of $2,500.
Your collateral is released according to the lender’s rules. Some institutions keep the entire original $2,500 locked until the loan is completely paid. Others gradually release portions of your collateral as you pay down the loan.
So no, you did not actually take out a real loan, but it will reflect on your credit report that you paid off a loan for the amount of $2,500 — which helps you build payment history.
Once the loan is paid off, your original $2,500 collateral is yours again. So it isn’t really a “refund” — the bank wasn’t charging you $2,500, it was holding your money as collateral.
AFTER completing Steps 4 & 5 from the To Do List, and ONLY AFTER EVERYTHING IS DELETED FROM YOUR REPORT — if you want to finance or refinance a car:
Search around for the car you like, test drive it, and ask questions about the vehicle. Specifically ask questions about your personal preferences. Remember, dealerships often buy cars from other dealerships and lots — so even if they don’t have the specific one or color you want, if you know a location who does, they’re usually willing to buy it from them and you can still finance through them.
Once you have the car you want picked out, go to the dealership or car lot and ask for a Purchase Order / Buyer’s Order (sometimes called a Purchase Agreement).
Do Not Skip This
If they ask why, let them know: “I’m obtaining outside financing through my current bank.” DO NOT LET THEM RUN YOUR CREDIT and DO NOT GIVE THEM YOUR SOCIAL!
Then go directly to Navy Federal, or whichever credit union or bank you did your secured loan with. You should be able to do this online as well.
Give them the Purchase Order and ask them directly for an auto loan. They will give you the PAPER CHECK 🧾 for the car. (Make sure you have the VIN number.)
There is no need for the dealership to run your credit and give you a million inquiries, because you don’t need to qualify for a loan through them. YOU HAVE THE CHECK! Your auto loan will be financed through your bank.
This same concept applies for refinancing a car. Just call or go to your bank and tell them you want to refinance.
Take the check to the dealership. Sign your papers 📑 and drive off blasting your favorite song 🎵 DON’T FORGET TO TAKE PICTURES AND GIVE ME A SHOUTOUT — tagging me on Facebook & Instagram. If you prefer to remain anonymous, just take pictures and videos and I’ll post them without tagging you.
To Do List Step 6
Pay Down Any Credit Cards That Are Over 30%
⚠️ If You Don't Have Any Credit Cards Yet — Skip To Step 7.
If you have completed Step 5, you can do this immediately after getting your money back from the Secured Loan.
Rule #1
NEVER SPEND WHAT YOU DO NOT HAVE
How To Pay Your Credit Card Bill Correctly
When It Comes To Paying Down The Balance There Are Two Types Of People:
✅ Type 1: Pay After Every Purchase
( THIS IS THE SAFER ROUTE )
Your balance is always low. It keeps your utilization near 0% at all times, which is best for your score.
💳 Type 2: Let It Build Up Then Pay
( WORKS IF YOU STAY DISCIPLINED )
Some people like seeing the money sit in their bank account rather than on the card. Just make sure you always pay before the statement date.
Pay down in this priority order:
• Preferably pay IN FULL
• If you can't pay in full, pay to where you only owe 10% or below
• If you can't get it under 10%, try to get it to where you only owe 30% or below
• If you can't get it under 30%, pay the minimum balance on time every month while you work the balance down
Why This Matters: Credit card utilization makes up 30% of your credit score. Keeping balances below 10% of your limit gives you the best score boost. Even getting under 30% will make a noticeable difference.
Utilization Calculator
See your utilization and get personalized payment options
Your Utilization Rate
To Do List Step 7
Get A Secured Credit Card
ONLY If You Don't Already Have At Least 2 Credit Cards With Limits At Least $500. The More The Better But Minimum $500. These are the banks I recommend getting a secured card from because they all graduate.
🏦 U.S. Bank Secured Visa Card
- Refundable security deposit determines your credit limit ($300–$5,000)
- Reports to all 3 bureaus — helps build payment history fast
- Graduates to an unsecured U.S. Bank card with on-time payments
- Cash-back rewards on gas & groceries (rare for a secured card)
🏛️ Bank of America Secured Card
- Refundable deposit ($200 minimum, up to $5,000) sets your limit
- Reports to all 3 bureaus
- BofA reviews account periodically — graduates to unsecured with deposit returned
- Easier approval if you already bank with BofA
🔒 Discover it® Secured Card
- 💳 Builds credit from scratch — still earns cash back (rare for secured)
- 2% cash back at gas & restaurants (up to $1K/quarter), 1% on everything else
- Cashback Match — Discover doubles all cash back at the end of year 1
- 🔁 Graduates to unsecured + deposit returned after on-time payments
- Requires deposit ($200+) — great for clients starting over or rebuilding
💳 Capital One (Pre-Approval Tool)
- Soft-pull pre-approval — check what Capital One cards you qualify for with no impact to your credit score
- Includes secured options (Platinum Secured) for fair / rebuilding credit
- Refundable deposit, automatic credit limit reviews
- Reports to all 3 bureaus — graduates to unsecured
Or you can get a secured credit card through whoever you currently bank with.
By graduate it means after 6-9 months of on time payment they'll give you your deposit back and send you a new credit card which you will now be using the Bank's money vs your own.
To Do List Step 8
Sign Up For 3-5 Credit Builder Accounts (the more the better)
Important Note: You want to make sure something is reporting to all 3 bureaus.
- THE PURPOSE OF THIS IS TO BUILD PAYMENT HISTORY & To Create A Good Credit Mix
- Before You Can Apply For Anything You Need To Establish Some Type Of Payment History.
- These are proven credit builder accounts. But I want to stress the importance that YOU DO NOT HAVE TO SPEND ALL OF YOUR MONEY ON THIS. Do whatever is comfortable within your budget.
- Get A Minimum 3, The More The Better But You DO NOT NEED THEM ALL. (you don't want all revolving or all installments)
Self - $35 - Installment (whatever fits your budget)
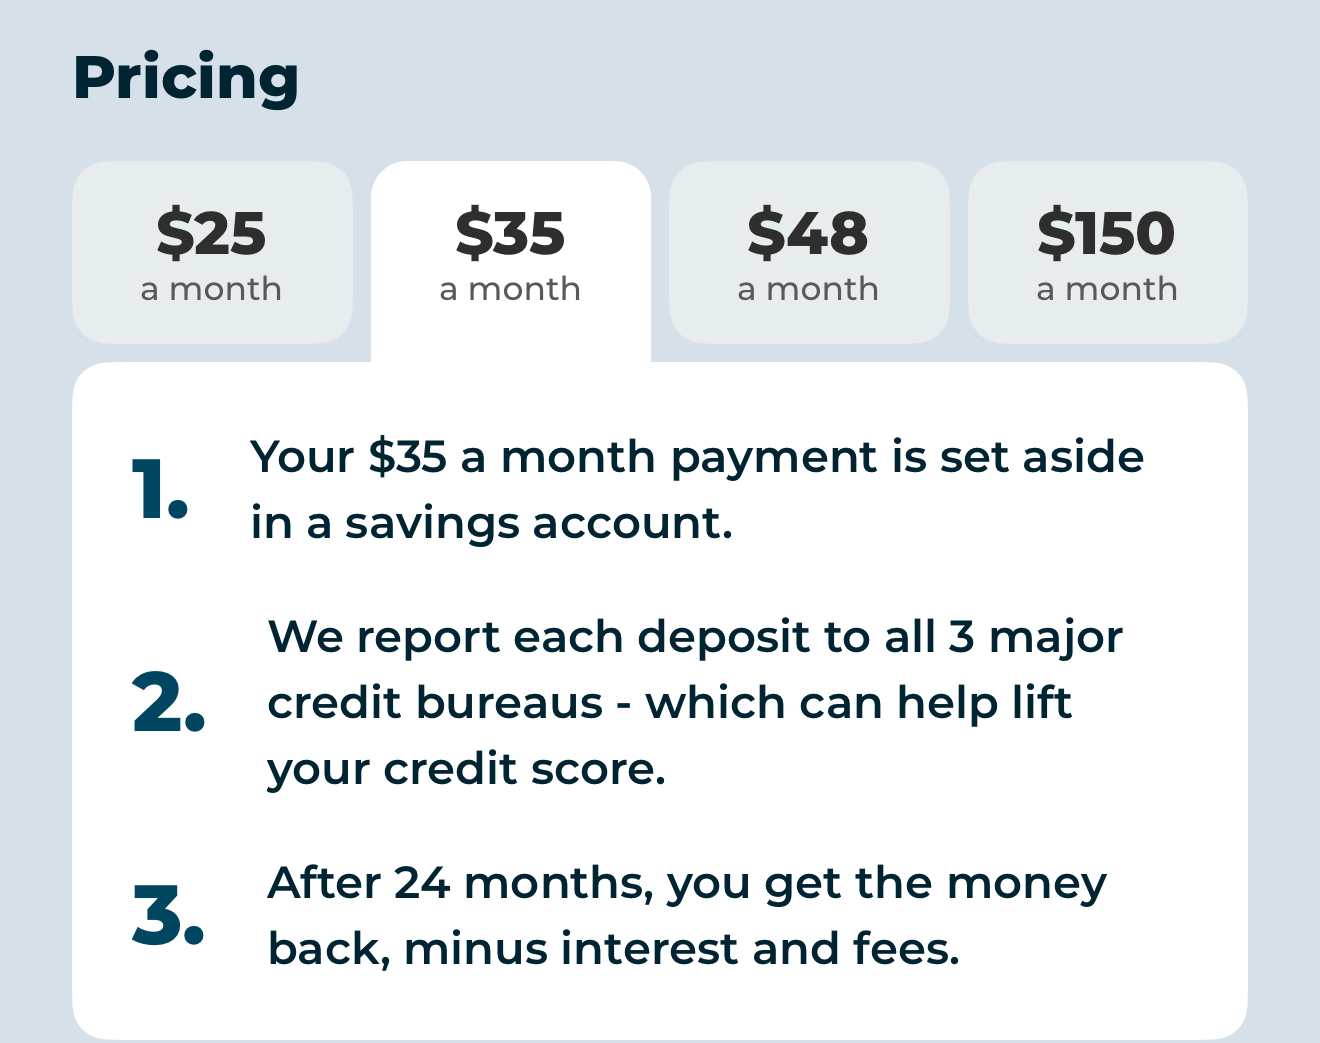
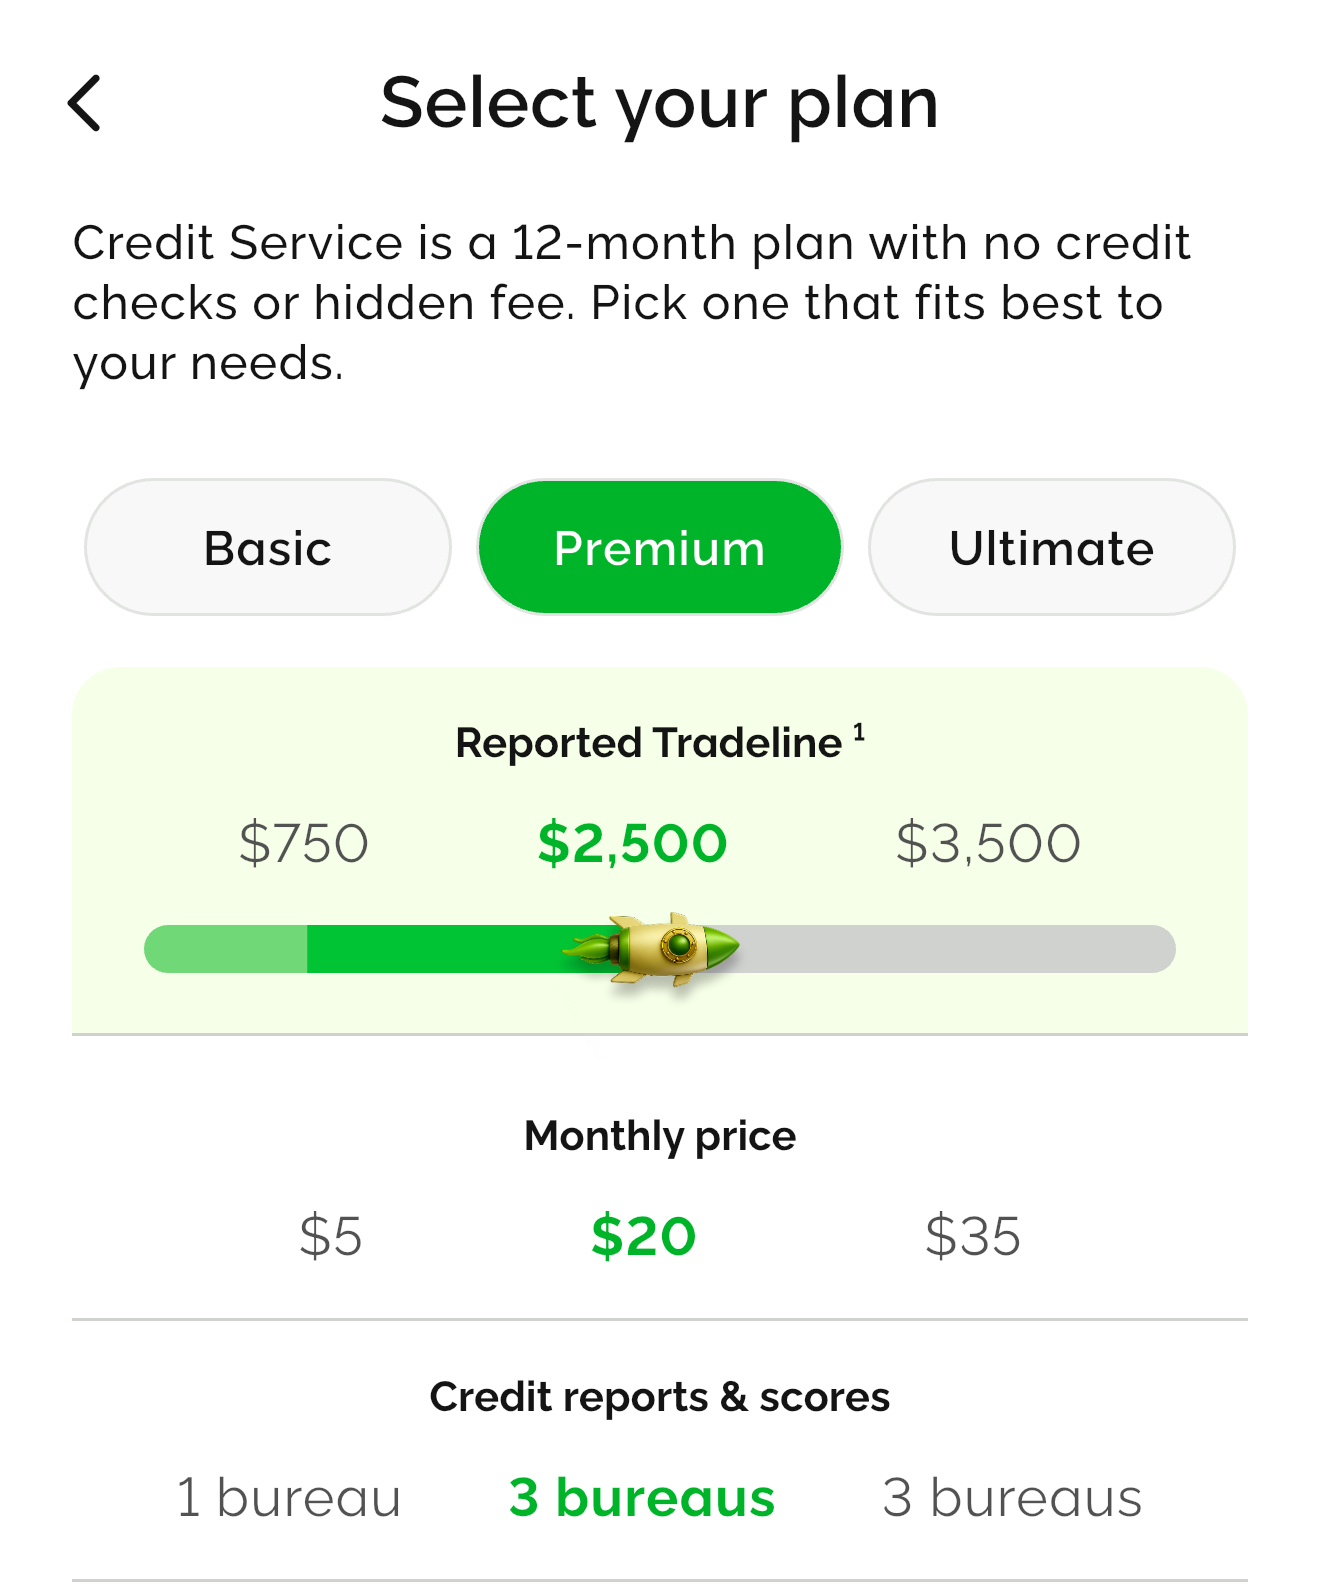
Kickoff - $20 (Revolving)
EXPERIAN BOOST - FREE TO JOIN
Experian Boost detects bills you pay like:
Phone & Telecom: Cell phone bills, Landline phone bills, Cable or satellite TV, Internet service
Utilities: Electricity, Gas, Water, Sewer, Trash / waste management
Housing: Rent payments (usually paid online or through a supported platform)
Subscriptions & Streaming: Netflix, Hulu, Disney+, Spotify, HBO / Max, Other streaming services
Insurance (monthly payments only): Auto insurance, Homeowners insurance, Renters insurance, Life insurance, Pet insurance
(Health insurance does NOT qualify.)
Those payments get added to your Experian credit file.
Sign Up For Experian Boost Here
AVA - Installment $26
Pay $26/mo for 12 months towards a secured Ava loan.
After 12 months, you'll get your $300 loan back - just like saving $300
Credit Strong - $30 (Installment)
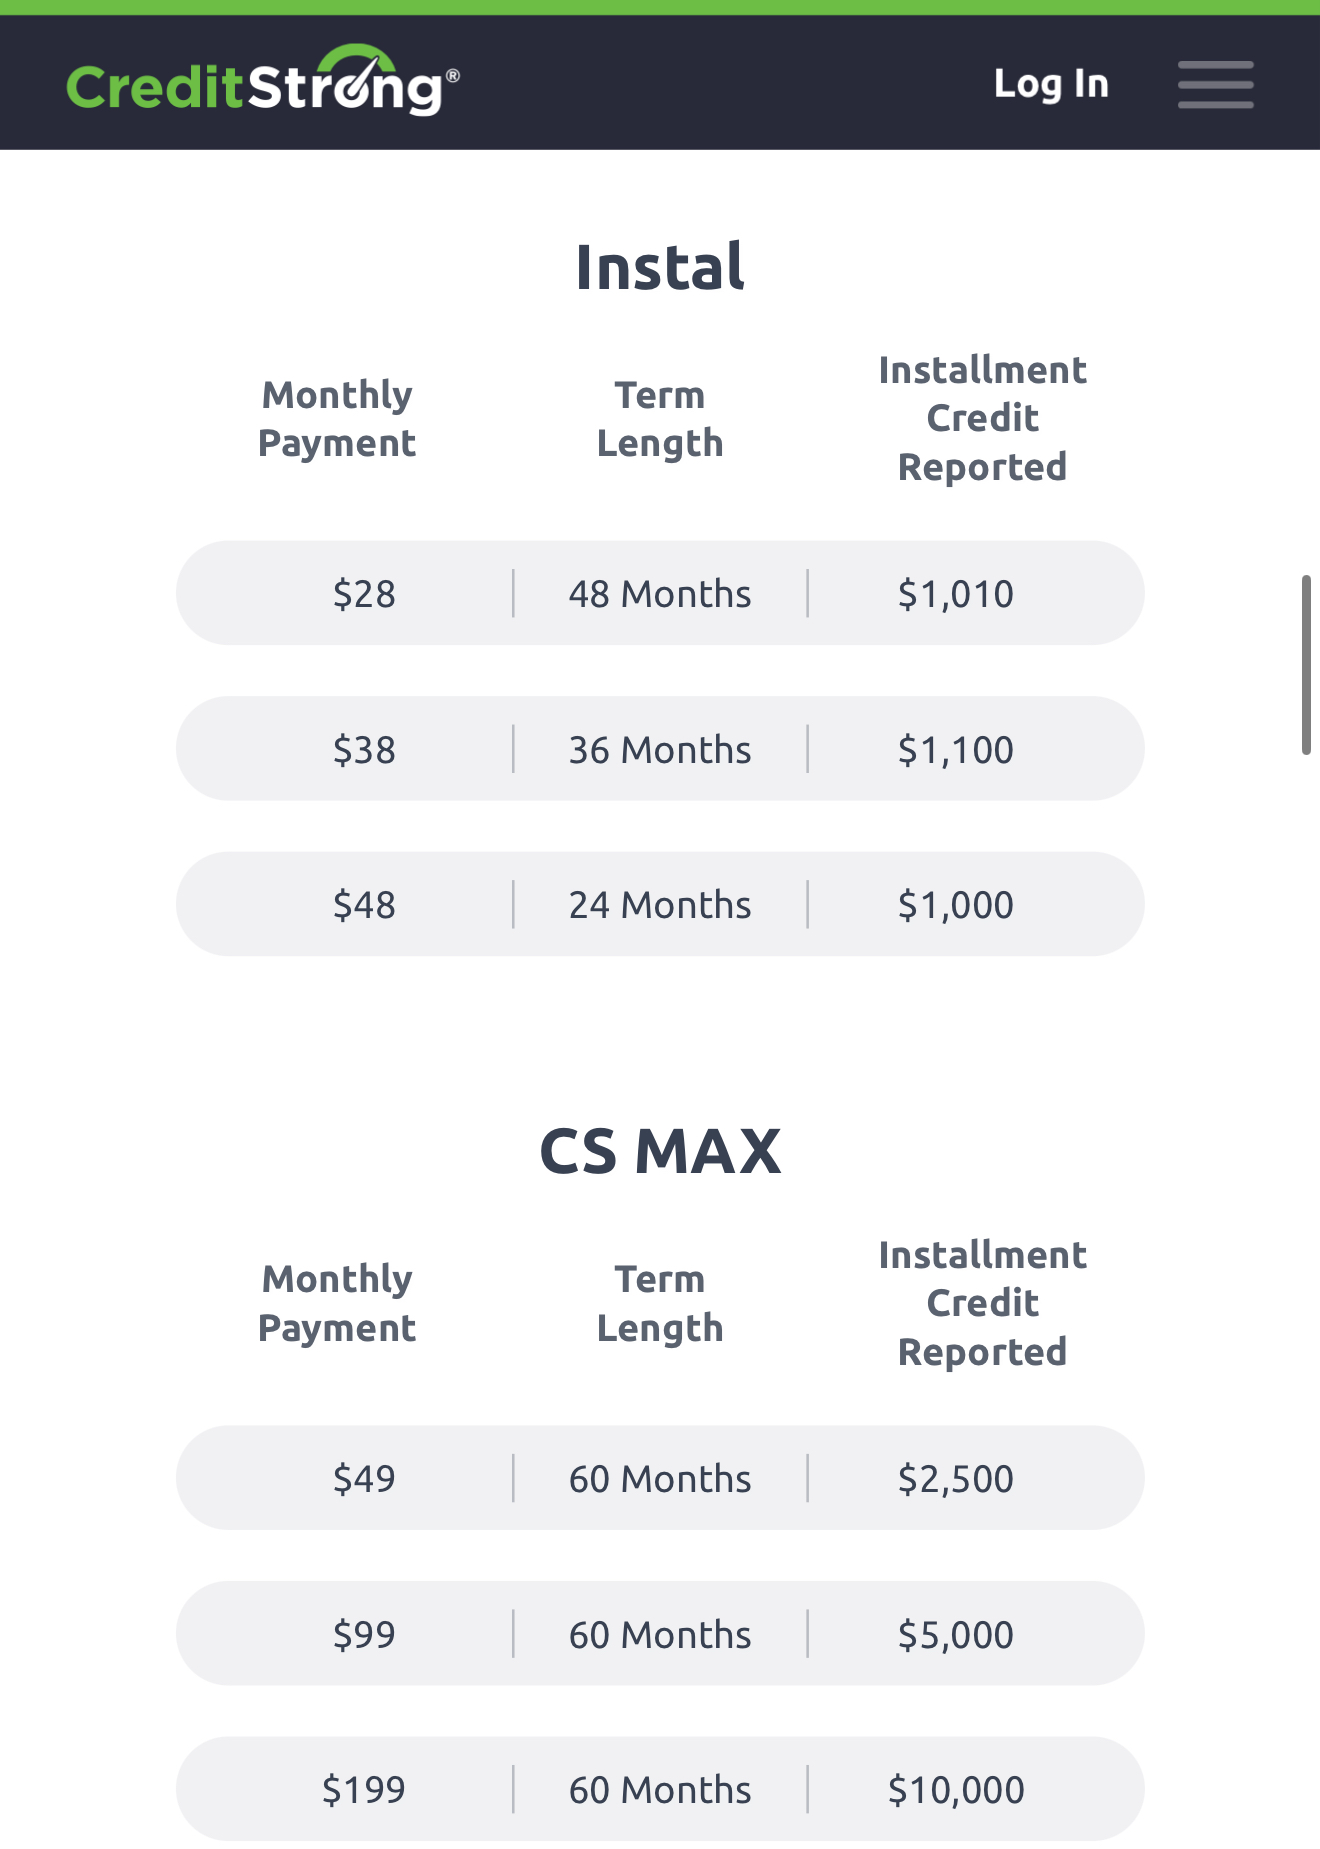
Sign Up For Credit Strong Here
When it comes to adding open credit such as rent and utility bills - ONLY DO THIS IF YOUR RENT & BILLS ARE ALWAYS PAID ON TIME
Credit Builder Account Summary
| Secured Loan | Installment - Whatever Is In Your Budget |
| Secured Credit Card | Revolving - Minimum $500 Limit (Which You Can Spend) |
| Kickoff | Revolving $20/Month |
| Tomo Credit Card | Revolving - Approvals Based off transactions |
| Credit Strong | Installment $30/Month |
| Ava | Installment $26/Month |
| Self | Installment $35/Month |
| Experian Boost | Open Credit (Phone, Cable, Light, Gas, Water, Auto Insurance, Homeowners Insurance, Subscription Apps Etc) |
If You Signed Up For Every Single Credit Builder Account It Will Cost You $111/Month. Look At It Like You're BUYING GOOD PAYMENT HISTORY.
To Do List Step 9
If you do not have student loans please skip this step and move on to Step 10
The size of your student loan doesn’t change the basic strategy.
Short Answer: This may seem like a lot because I am providing a lot of knowledge for those who may not understand exactly how student loans work. Read through each section below.
Whether you owe $3,500, $35,000, or $100,000+, you need to do 11 things:
THE SIMPLE FORMULA 🧠
- KNOW WHAT YOU OWE 💵
- KNOW WHEN PAYMENTS ARE DUE 📆
- NEVER IGNORE THE SERVICER 📄
- CHECK FOR FORGIVENESS PROGRAMS BEFORE PAYING EVERYTHING OFF 🏛️
- MAKE THE REQUIRED PAYMENT ✅
- UNDERSTAND HOW MUCH INTEREST IS ACCRUING 🧮
- PAY EXTRA WHEN POSSIBLE 💸
- TARGET HIGH-INTEREST LOANS FIRST 🔎
- USE EXTRA INCOME TO ATTACK THE BALANCE 🧾
- REVIEW YOUR BALANCE EVERY MONTH 🧐
- REPEAT UNTIL THE BALANCE = $0 👏🏾
If you want to know what this actually looks like step by step… I will explain in more detail below ⬇️
- Ignoring emails from loan servicer
- Forgetting to update their address, phone number, or email
- Assuming payments don’t start yet
- Thinking loans are still paused (like during COVID)
- Drop below half-time enrollment without realizing their grace period may begin
- Know a payment is due but ignore it because money is tight
- Don’t contact their servicer when they can’t afford the payment
👉 Late = 30 days past due → hits your credit
IMPORTANT: Missing a payment makes a federal student loan delinquent. Federal Student Aid states that delinquency of 90 days or more can be reported to the three major credit bureaus.
To avoid this you have to actually begin paying down the loan. If you can’t—The solution is to address the problem BEFORE it reaches that point.
If you know for a fact the next upcoming months you won’t be able to make payments on your loans…DO NOT just ignore it ❌
In many cases, lenders are willing to work with borrowers who communicate proactively. If an agreement is approved, it can help bring the account back into good standing and may positively impact your credit over time.
Instead Apply for:
- 💰 Income-Driven Repayment (IDR)
- ⏸️ Deferment
- 🛑 Forbearance
- Consolidate your loan
- Set up a payment arrangement
- Move the past-due balance to the end of the loan
- Offer any hardship assistance programs to prevent additional late payments from reporting
👉 This keeps your account in good standing
Here’s a recommended script:
If your credit scores have already dropped due to student loan late payments, contact your student loan servicer immediately. Explain that you are currently trying to qualify for housing and that the late payments are negatively affecting your approval chances.
If it applies to you, let them know that you were unaware payments had resumed and believed the loans were still paused from the COVID period. Then respectfully ask if there are any options available to help reverse the late payments or prevent further negative reporting.
Most importantly, once an arrangement is made, make sure you begin making payments consistently — if money is still tight consider paying at least $5 more than the amount of interest that accrues each month, or $5 more than your required monthly payment, whichever is greater. This helps ensure your balance continues to DECREASE instead of staying the same or growing.
📈 Student Loan Payment Calculator
Student Loan Payment Calculator
Estimate your daily interest, monthly interest, payment breakdown, extra-payment target, and how much you need to pay to bring your balance back to the original loan amount.
Enter Your Loan Information
If you cannot make a large payment to bring the account back to the original loan amount, your first priority should be making at least your required payment so you can help keep the account current.
Your Estimated Results
To Do List Step 10
Apply For Credit Limit Increases
How Credit Limit Increases Work
When a lender reviews your account and decides you can responsibly handle more credit, they increase your limit.
Two Types of Credit Limit Increases
Automatic Credit Limit Increase
The bank increases your limit without you asking.
They usually look at:
- Payment history
- Credit utilization
- Income changes
- Account age
- Overall credit profile
Typical timeframe: 3-6 months of on-time payments (you can call customer service to find out exactly when you will qualify for your next Credit Limit Increase)
Requested Credit Limit Increase
You log into your account or call the bank and ask for a higher limit.
The lender may do:
Soft Pull (no score impact) - Common with many cards today
Hard Pull (temporary score drop) - Some lenders still do this, Navy Federal is one of them.
Factors Lenders Look At
When deciding whether to increase your limit, lenders review:
1. Payment History - Consistent on-time payments
2. Utilization - Ideally below 30%, best under 10%
3. Income - Higher income = higher limits
4. Account Age - Older accounts are more trusted
5. Spending Patterns - If you actually use the card
Example: If someone has a $500 limit but only spends $20 a month, the bank may not increase it because the limit isn't being utilized.
What To Do?
There are two ways you can trigger the bank for a credit limit increase. (there is not right or wrong answer)
Option A:
Make a large purchase, for example an expensive Louis Vuitton Bag - wait until the payment posts and then return the bag.
Option B:
Make large payments for the next 3-6 months & pay the balances back down before the statement date.
Remember not to spend What You Don't ALREADY HAVE. Take Christmas or Birthday shopping as an example. If you were already planning to spend a lot of money due to Christmas, this would be the perfect time to max out your credit cards and pay them back off. But don't just go spending unnecessary money just to get a credit limit increase - it's not that serious.
The Point Is To Get The HIGH CREDIT Section On Your Credit Report To Reflect As If You're Actually Spending Up Most Of Your Limit. As Long As This Is Paid Down 3 Days Before The Statement Date It Will Not Affect Your Credit Score.
To Do List Step 11
Apply For New Credit
By this stage, most clients have reached what we call the Execution Phase of the program. This is the point where your credit profile should be in a much stronger position, and you may begin strategically applying for new credit.
Before applying for the specific credit product you ultimately want, there are a few steps that can help increase your chances of approval and potentially lead to higher approval amounts or lower interest rates.
You may consider adding one or two additional tradelines or credit cards to your profile — unless you already have 3–5 active credit cards, which is typically an ideal range for a strong revolving credit profile.
Another option is applying for a personal loan. This can serve two purposes:
- Paying down existing credit card balances, which can improve your credit utilization ratio
- Strengthening your relationship with the lender, which may increase your credibility when applying for larger financing (such as a business loan) in the coming months
As long as all negative items have been successfully removed from your credit report, it is generally safe to begin applying for new credit.
Optional — Need Help Applying?
If you would like assistance with the application process, you are welcome to book a consultation. I work directly with relationship managers at various financial institutions and understand how to structure applications in a way that can help maximize approval amounts.
Please note: if I assist you with securing approval for any credit cards or loans, my service fee is 10% of the approved amount.
However, this service is completely optional. You are more than welcome to apply on your own — and by this stage of the program, most clients are in a strong position to qualify independently.
To Do List Step 12
Credit Card Ladder 🪜
Side Note: YOU DO NOT NEED EVERY LAST CREDIT CARD LISTED…. These Are Just EXAMPLES ‼️
Important Reminder
While there's nothing wrong with applying for maybe 2–3 credit cards in the same day, realistically speaking you generally want to wait at least 6 months before every new inquiry.
New credit can lower your CREDIT HISTORY, and too many inquiries back-to-back make you look desperate for money.
So please don't go too crazy just because you have a good credit score and a clean credit report.
Starter Cards 💳
These are the cards we will use to get our credit going 🪜 — considered ENTRY LEVEL CREDIT CARDS. These are specifically for people with bad credit, decent credit OR NO CREDIT.
💳 Capital One Platinum
- No annual fee — designed for fair / rebuilding credit
- Automatic credit limit increase after on-time payments
- Pre-approval with no hard inquiry first
- Reports to all 3 bureaus (great for building profile)
🏦 Navy Federal Platinum Card
- VERY LOW APR (one of the lowest in the industry)
- No annual fee — great for balance transfers / debt payoff
- Strong limits $2,000–$10,000 with Navy Federal relationship
⚠️ Must be eligible for Navy Federal (military, family, etc.)
Apply Now →✨ Capital One Quicksilver
- Unlimited 1.5% cash back on EVERYTHING
- $200 welcome bonus | 0% intro APR ~15 months | No annual fee
- Good upgrade path from Platinum — daily spender card
🏃 Chase Freedom Rise
- Designed for new credit / low credit history
- Helps build relationship with Chase (VERY important bank)
- Cashback rewards | No annual fee | Higher approval odds if you bank with Chase
🔒 Discover it® Secured Card
- 💳 Builds credit from scratch | Still earns cash back
- 🔁 Can upgrade to unsecured + get deposit back | No annual fee
- Requires deposit ($200+) — Best for clients starting over or rebuilding
👎 Bad Starter Cards (crazy interest rates, low limits) — AVOID: Open Sky, Credit One, First Premier, Store Cards
Beginner Cards 💳 (700+ Credit Score, 2–5 Cards MAX)
By the time you get to this point you should be at a 700+ credit score from 2–5 cards MAX. These cards are the next step up — better rewards, higher limits, and stronger long-term relationships with the major banks.
🍽️ Capital One Savor
- High cash back on dining, entertainment, streaming, groceries
- 💰 Unlimited cash back (no caps) | Strong welcome bonus | No foreign transaction fees
🔵 Discover It
- 5% rotating categories | Cashback Match (DOUBLE all cash back first year)
- Known for credit limit increases over time | No annual fee
- 👉 One of the STRONGEST beginner cards for rewards + growth
💰 Navy Federal Cash Rewards (Up To $25,000)
- Up to 2% cash back | $250 bonus | HIGH LIMITS (10K–25K+)
- Rewards don't expire | No annual fee | Best for funding plays + BIG limits early
⚠️ Must qualify for Navy Federal (military / family)
Apply Now →✈️ Chase Sapphire (Min $5,000 Limit)
- Top-tier travel rewards | 3X dining, 2X travel | Huge welcome bonus (60K–75K+ points)
- Travel protections | $5,000 minimum limit (Visa Signature)
- 👉 Best for travel + building a premium credit profile
Amateur Credit Cards 💳 (Higher Limits $10,000+ | 3–6 Months)
After 3–6 months of consistent payments and clean profiles you can step up to these. Expect higher limits ($10,000+), stronger rewards, and bigger sign-up bonuses. These are the cards that start unlocking real funding power.
💵 American Express Blue Cash Everyday®
- 💰 3% Cash Back on groceries, gas, online shopping | $0 Annual Fee
- 0% Intro APR (12–15 months) | Welcome bonus $150–$250+
- 👉 Good for: beginners, everyday spenders, clean profiles
🍎 Apple Card (Up To $30,000)
- 2% Cash Back on Apple Pay | 3% at Apple + select partners
- 📲 Instant approval (soft pull first) | Daily Cash paid out daily
- Can get limit increases fast | Great for Apple product financing (0% plans)
🔄 Chase Freedom Flex
- 💰 5% rotating categories | 3% dining + drugstores | 5% travel (Chase portal)
- 0% APR ~15 months | $0 Annual Fee | $200+ bonus
♾️ Chase Freedom Unlimited
- 💰 1.5% unlimited cash back on EVERYTHING | 3% dining + drugstores
- 0% APR ~15 months | $0 Annual Fee | $200–$250 bonus
- 👉 This is your "daily swipe" card — no thinking, just earn on everything
Free Travel Cards 💳 (Annual Fees, MAX REWARDS, Best Benefits)
The Goal Is To Travel FOR FREE. Only if you travel at least 1–3X per year.
🥇 American Express Gold Card ($325/yr)
- 🍽️ 4X Points on Dining Worldwide | 🛒 4X Points on Groceries
- 🎁 Monthly credits (Uber, dining, etc.) — total $500+ yearly value
- Can out-earn the annual fee with credits | Builds strong Amex relationship
- 👉 Perfect for stacking points FAST — daily spender card
👑 American Express Platinum Card ($895/yr)
- ✈️ 5X Points on Flights & Hotels | 🛫 1,400+ Airport Lounges Worldwide
- 💼 NO preset spending limit | Airline, Uber, Hotel, Streaming credits
- 👉 Best for business owners, travelers, and high spenders
⚓ Navy Federal Flagship Card (Up To $50,000)
- 💳 HIGH LIMIT approvals | ✈️ 3X Points on Travel | 💰 2X Points on Everything
- FREE Amazon Prime (~$139) | TSA PreCheck / Global Entry credit (up to $120)
- Low annual fee (~$49) | No rewards cap or expiration
- 👉 Hidden gem for funding + travel combo
Business Credit Cards 💳
Max Travel, Crazy Rewards, High Limits, And 0% Offers 8–18 Months
| Card | Best For | Key Perk |
|---|---|---|
| Capital One Venture X Business | Best overall travel | 2X–10X miles, $300 travel credit, lounge access |
| Amex Business Platinum | Status + big funding | 5X on flights/hotels, 1,500+ lounges, no preset limit |
| Chase Ink Business Preferred | Chase ecosystem | 3X travel/shipping/ads, $1K+ signup bonus |
| Chase Ink Business Cash | Easy approval + 0% | 0% APR 12 months, 5% cash back, $0 annual fee |
| Chase Ink Business Unlimited | Simple stacking | 0% APR 12 months, 1.5% unlimited, $750 bonus |
| Amex Blue Business Cash | Clean profiles + Amex | 0% APR 12 months, 2% cash back, no annual fee |
| Amex Blue Business Plus | Low-key travel points | 0% APR 12 months, 2X points everything, no annual fee |
| U.S. Bank Triple Cash Business | Longest 0% offer | 0% APR 12–18 months, 3% categories, $500 bonus |
| BofA Business Advantage Travel | Travel + 0% combo | 0% intro APR, travel rewards, no annual fee |
| Wells Fargo Signify Business | High spend + simple | 0% APR 12 months, 2% flat cash back, no annual fee |
To Do List Step 13 — Interested In Business Funding? 💼
A lot of people think having a good credit score and a clean credit report automatically guarantees business funding, but that is not always the case. You can have excellent personal credit and still get denied if your LLC is not set up properly. Your personal credit may help get you in the door, but a properly structured LLC helps determine how much trust and funding potential your business actually has. That said, I will explain how to properly set up your LLC to MAXIMIZE the amount of funding your business can potentially receive.
Start Now Or Wait?
Truthfully this is a step that can be done immediately, especially if you already have a business that is consistently generating a Minimum 10K/Month. You do not necessarily have to wait to complete the other steps to begin this step.
However, if you do not currently have an established business, sometimes it may be better to wait before starting your LLC — which is why this step was placed towards the bottom of the list. There are pros and cons to both decisions, and ultimately you have to decide what is in your best interest based on your goals, situation, and budget.
The 2-Year Rule 📆
One important thing to understand is that banks and lenders typically prefer to see LLCs that have been established for at least two years. The reason is that many new businesses fail within the first couple of years, so longevity helps show stability and credibility.
Because of that, when it comes to applying for funding, the longer your LLC has been established, the stronger your profile may appear to lenders. For example, there is not a huge difference between an LLC that has been open for 3 months, 6 months, or even 9–12 months — because either way, the business is still considered relatively new and under that 2-year mark.
However, if you start your LLC now, you are giving yourself a head start toward reaching that 2-year milestone. Waiting 6 months to start simply means you will also delay reaching that point by another 6 months.
The Cost Of Owning An LLC 💵
At the same time, it is important to understand that owning an LLC comes with expenses. You may have monthly or yearly costs such as:
- Business email
- Business website
- Business phone number
- Business address
- Domain and hosting fees
- Other business-related expenses
Now, many of these expenses can potentially become tax write-offs, but you still need to make sure they fit comfortably within your current budget.
So if these costs will not hurt you financially, then I would say go ahead and start your LLC now.
But if money is tight at the moment, I would personally recommend focusing on fixing and strengthening your personal credit first. Once your personal credit improves and you are approved for credit cards with strong limits, you can then use that leverage to help fund everything that comes with building your business properly.
That is the route I would recommend for people who may benefit more from waiting a little longer before starting their LLC.
At the end of the day, there is no right or wrong answer. The best decision is the one that aligns with your financial situation, your goals, and your overall strategy.
Setting Up Your LLC PROPERLY
Do These In This EXACT ORDER. Because When You Do Step 6, You Will Need To Put Steps 1–5 On The Application.
| Step 1 | Business Name | Not In A Restricted Industry |
| Step 2 | Business Address | Brick & Mortar |
| Step 3 | Business Phone | 800 Number |
| Step 4 | Business Email | Not A Gmail |
| Step 5 | Website | Nothing Related To Anything Restricted (Social Media Not Enough) |
| Step 6 | Apply For Business Entity | LLC |
| Step 7 | E.I.N | Your business social |
| Step 8 | Open Business Checking & Savings Bank Account | No Personal Bank Account. (MUST NOT BE IN CHEXSYSTEMS) Put $100 In Checking & Savings |
| Step 9 | Duns & Bradstreet Number | Making Sure Your Company Is Verified |
| Step 10 | Ask For Money | You have 30 days to remove the inquiries before they hit your credit report |
Picture A $50,000 Line Of Credit Waiting On You. For Every Red Flag 🚩 You Lose $5,000
| Find Out If Your Business Is In A High Risk Industry | $50,000 | https://fairfigure.com/blog/low-risk-naics-codes |
| Wrong Business Name? -$5,000 | $45,000 | Search For The Business Name Here — https://apps.ilsos.gov/businessentitysearch/ |
| No Business Email? -$5,000 | $40,000 | Google Workspace — $7–$14/Month https://workspace.google.com/business/signup/welcome |
| No Business Address? -$5,000 | $35,000 | Google Registered Agent For Your State ( Ex: Registered Agent Illinois ) |
| No Business Number -$5,000 | $30,000 | Google Voice, Grasshopper, RingCentral, SideLine, TextNow |
| No Business Website -$5,000 | $25,000 | Contact Harry — He's The One Who Created My Website. harry-castaner.vercel.app |
| No Duns & Bradstreet -$5,000 | $20,000 | Get Your D&B Number https://www.dnb.com/en-us/smb/duns/get-a-duns.html |
| No Business Bank Account | $0.00 | Must Have An ACTUAL BUSINESS BANK ACCOUNT To Reach A Business Loan |
Ready To Apply For Funding?
With this information I have now educated you on how to properly set up an LLC, establish relationships with banks, and position yourself to qualify for business funding. My goal is to teach clients how to apply independently.
However, if you choose to have me assist directly with applications, I charge a 10% success fee based on the approved amount.
I also work with relationship managers at major institutions, including:
These relationship managers are the individuals who actually review and approve applications and say APPROVED OR DENIED. I refer my clients directly to them. Due to them being my relationship managers, essentially the more money you get approved for, the more they make as well — which is why although you may have to pay a 10–15% referral fee, it can still help you lock in a substantial amount of capital for your business.
Additionally, I offer tradelines & shelf corporations, which function similarly to tradelines but for an LLC. Please book a consultation if you are interested in one of those, or going through one of my relationship managers for funding.
To Do List Step 14 — Congratulations 😎🥂
Congratulations On Completing Your Program!
By this time you should be somewhere between a 700–750+ Credit Score.
✅ Ready For Funding?
If you are a client who is ready to pursue personal or business funding, you should be able to apply independently. However, if you choose to have me assist directly with applications, I charge a 10% success fee based on the approved amount.
I also work with relationship managers at major institutions, including:
These relationship managers are the individuals who actually review and approve applications, and I refer my clients directly to them — which means larger approvals.
I also offer tradelines & shelf corporations, which function similarly to tradelines but for an LLC. If you are interested, feel free to book a consultation.
🙌 Not Interested In Funding? That's Totally Fine.
Please understand that you're pretty much done. At this point the only things that will help you strengthen your profile are:
- Adding a Mortgage — which is NOT mandatory.
- The only other thing that will help you is TIME.
✅ What To Keep Doing From Here:
- Continue to keep your utilization down
- Keep making on-time payments
- Let time do its thing — payment history builds over time
- Stay away from new late payments & collections
- Stay away from unnecessary inquiries
That's literally it. There's no extra special sauce. 🎯
Congratulations On Completing Your Program 😎🥂
You put in the work. Now enjoy the results and build on them.
Digital Library
Essential links, tools, and resources for your financial journey
Essential Links & Resources
Credit Building Services:
Customer Support:
Phone: (773) 963-6872
Email: support@thejasminemovement.org
Availability: By Appointment Only
Business Hours: Mon – Thu: 12PM – 6PM
How To Reach Our Team
Scheduling, customer support, and social media
- Please do not send messages through Facebook Messenger or Instagram for service inquiries.
- We do not accept unscheduled phone calls. Book a consultation for the most effective communication.
- Due to client volume, responding to unscheduled calls and messages is not feasible while maintaining service quality.
- For this reason, all questions and concerns must be addressed through a scheduled consultation.
- As an active client, consultations are available at no additional cost.
- Our team may not be available outside of posted business hours.
Schedule Your Consultation:
Contact Information
Email: support@thejasminemovement.org
Phone/Text: (773) 963-6872
Please allow 24-48 hours for a response. Text or email is preferred.
Social Media
Instagram: @thejasminemovement
TikTok: @thejasminemovement
Facebook: The Jasmine Movement
— The Jasmine Movement Team